

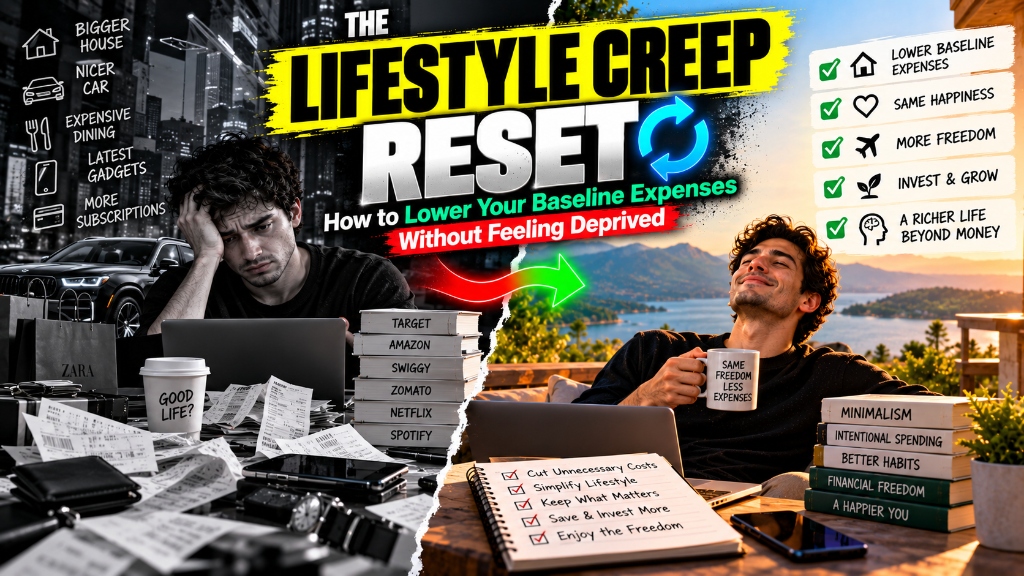
The Lifestyle Creep Reset: How to Lower Your Baseline Expenses Without Feeling Deprived
Execute a proven lifestyle creep reset plan. Lower fixed overhead, audit housing and auto bills, and stop lifestyle inflation without feeling deprived.
Educational Resource: This guide does not constitute financial or legal counsel.
Direct Answer: A lifestyle creep reset plan is a systematic process for deflating inflated monthly living costs by renegotiating large structural fixed commitments (such as housing, auto payments, and recurring insurance contracts) rather than practicing petty micro-frugality. By eliminating silent recurring overhead, you restore a 30% to 50% savings rate while preserving daily lifestyle enjoyment.
When you received your first professional promotion or salary bump, you promised yourself that the extra income would go straight into your investment portfolio.
Yet six months later, your bank balance tells an entirely different story.
Your rent is higher, your car lease is more expensive, your dining receipts have doubled, and your monthly checking account buffer feels just as tight as it did when you earned half your current salary. Despite earning more money than ever, you are saving virtually nothing extra.
This insidious phenomenon is known as lifestyle creep (or lifestyle inflation). As income rises, former luxuries quietly morph into perceived necessities, ratcheting up your baseline burn rate until your financial freedom date is pushed decades into the future.
Most budgeting advice tackles this problem with miserable micro-deprivation: skipping four-dollar coffees, canceling music streaming, or reusing sandwich bags. This approach fails because willpower is a depleting resource.
The sustainable solution is structural fixed-cost deflation. Here is how to execute a 30-day lifestyle creep detox, permanently lower your living overhead, and institute automated defenses against future inflation.
The Slow Boil: How a 20% Raise Turns into Zero Extra Savings
Lifestyle creep occurs through the slow expansion of recurring baseline commitments that absorb income gains without delivering lasting happiness.
The psychological engine powering lifestyle inflation is the hedonic treadmill: human beings adapt with remarkable speed to upgrades in comfort. The luxury apartment with floor-to-ceiling windows produces a dopamine rush for four weeks; by month three, it simply becomes your ordinary living environment. The premium sports car provides excitement for a month; by month six, it is just a vehicle stuck in morning highway traffic.
Unfortunately, while your emotional satisfaction resets to baseline, the financial commitment remains permanently elevated.
Consider an employee who earns an $80,000 salary and receives a promotion to $100,000 (a $20,000 gross annual raise, netting roughly $1,150 extra per month after taxes):
- They lease a new vehicle: +$450/month.
- They move into a luxury apartment building: +$500/month.
- They upgrade to high-end gym memberships and meal kit services: +$200/month.
Within 90 days, the entire $1,150 monthly raise is completely consumed by new recurring contracts. Their net savings rate remains exactly 0%, while their vulnerability to unexpected income disruptions has increased substantially because their required monthly survival threshold is now higher.
Fixed vs. Variable Costs: Why Eliminating Recurring Commitments Trumps Micro-Frugality
Eliminating recurring fixed commitments creates permanent, effortless cash flow savings, whereas cutting discretionary variable expenses requires continuous, exhausting willpower.
Traditional personal finance focuses obsessively on variable micro-expenses:
- “Do not buy lattes.”
- “Eat out only once a month.”
- “Cut your grocery budget by $20 a week.”
Every single time you deny yourself a coffee or dinner with friends, you burn cognitive energy. Eventually, decision fatigue sets in, leading to revenge spending sprees that obliterate months of discipline.
Fixed costs, by contrast, operate on an entirely different economic principle. When you renegotiate your car insurance, refinance a high-interest balance, or move to an apartment that costs $400 less per month, you make one single decision that pays dividends automatically every 30 days. You save $4,800 annually without having to exercise willpower once.
The Housing and Auto Audit: Refinancing, Downsizing, and Insurance Renegotiations
Targeting housing and transportation expenses provides the highest financial leverage because these two categories represent over 50% of the average household budget.
If you want to reset your lifestyle baseline quickly, start where the numbers are largest:
1. The Auto Payment Reality Check
The average new vehicle payment in the United States exceeds $700 per month, with terms extending to 72 or 84 months. Driving an expensive depreciating asset financed on credit is the primary wealth destroyer of the middle class:
- The Audit: If your car payment, full-coverage insurance, and fuel exceed 15% of your net monthly take-home pay, you are overextended.
- The Reset: Sell the luxury lease or financed SUV, pay cash for a reliable three-to-five-year-old certified pre-owned vehicle (like a Toyota or Honda), and pocket $500 to $800 in monthly savings permanently.
2. Auto and Home Insurance Shopping
Insurance carriers rely heavily on customer inertia, quietly increasing premiums by 8% to 15% annually during policy renewals.
- Set aside two hours on a Saturday to input your current policy declarations into an independent insurance comparison broker (such as Policygenius or an independent local agent).
- Bundling home and auto policies or raising your comprehensive deductible from $500 to $1,500 often saves $600 to $1,200 annually with zero change in actual protection.
3. The Housing Freeze
Housing is the anchor expense that dictates utility bills, furnishing costs, and property taxes. If you are renting, commit to staying in your current, well-priced home for an additional two years rather than upgrading to a newer building just because your salary increased.
The “Subscription Guillotine”: The 60-Day Cancel-and-See Experiment
The subscription guillotine involves canceling every non-essential recurring subscription simultaneously and waiting 60 days to see which ones you genuinely miss.
Over time, households accumulate silent recurring leaks: multiple streaming video platforms, specialized music subscriptions, cloud storage tiers, digital gym apps, beauty boxes, and software tools. Individually, they cost $12 to $35; collectively, they often drain $300 to $600 per month.
Instead of debating whether you “need” each service individually, execute this 60-day experiment:
- Cancel Everything Non-Essential: Cancel Netflix, Disney+, Spotify, specialized newsletter subscriptions, meal deliveries, and fitness apps. Keep only core utilities (electricity, water, broadband internet).
- Do Not Panic: You are not swearing off these services for life. You are simply establishing a clean baseline.
- The Friction Rule: If 30 or 45 days pass and you find yourself constantly wanting to use a specific service for work or meaningful recreation, re-subscribe with full intentionality.
- The Discovery: Most people discover that 70% of the services they were paying for were never missed. They were simply running on autopilot.
Comparison Table: Temporary Deprivation vs. Structural Fixed-Cost Reset
| Operational Strategy | Temporary Extreme Deprivation | Structural Fixed-Cost Reset Plan |
|---|---|---|
| Target Expenses | Dining out, morning coffees, social events | Housing, auto loans, insurance, subscriptions |
| Effort Required | Exhausting daily willpower and self-denial | A one-time structural renegotiation |
| Long-Term Sustainability | Low (High risk of rebound overspending) | Permanent (Effortless passive compounding) |
| Impact on Mental Well-Being | High feelings of poverty and isolation | Zero reduction in daily lifestyle quality |
| Monthly Savings Magnitude | $50 to $150 / month | $600 to $1,800+ / month |
| Scalability | Hard ceiling on how much coffee you can cut | Scales directly with major budget lines |
Implementing the “Reverse Raise” Strategy for Future Promotions and Bonuses
The reverse raise strategy permanently protects against future lifestyle inflation by automatically redirecting 80% of every new income increase into investments before it hits checking.
When you know you have an upcoming raise, bonus, or client retainer bump arriving, your financial defense must be set up before the new paycheck lands in your bank account:
- Calculate Your Net Increase: If your annual promotion adds $800 to your net monthly paycheck, calculate 80% of that figure:
$800 x 0.80 = $640 - Increase Automated Investments Immediately: Log into your employer payroll portal or brokerage and increase your monthly 401(k), HSA, or automated index fund deposit by $640 on the exact effective date of the raise.
- Enjoy the Remaining 20% Guilt-Free: Allow the remaining 20% ($160 per month) to flow directly into your checking account. This small increase allows you to enjoy a perceptible upgrade in lifestyle (better groceries, extra dinners out) while guaranteeing that the vast majority of your career growth accelerates your financial independence timeline.
Designing a “Guilt-Free Splurge Fund” to Prevent Rebound Overspending
A guilt-free splurge fund acts as a psychological pressure valve that prevents rigorous budgeters from abandoning their long-term savings systems.
Total financial restriction functions exactly like an extreme crash diet: if you eliminate all carbs and sweets, you inevitably end up bingeing on an entire box of cookies at midnight.
To maintain a low fixed-cost lifestyle for years, you must build intentional joy into your system:
- Create a Separate Splurge Bucket: Direct 5% to 10% of your take-home pay to a secondary checking account or cash envelope labeled
Guilt-Free Splurge. - Zero Rules Allowed: The only rule governing this money is that it cannot be saved for bills. You are required to spend it on whatever brings you pure, unadulterated joy: weekend spa trips, high-end electronics, vintage vinyl records, or treating your parents to an extravagant dinner.
- Psychological Freedom: Because your structural fixed costs are low and your 80% automated savings are already locked away, you can spend every dollar in this fund with complete freedom from guilt.
Frequently Asked Questions
How do I know if lifestyle creep is ruining my savings?
You are suffering from lifestyle creep if your annual income has increased over the past two to three years, yet your net savings rate (percentage of take-home income saved) has declined or remained flat while your monthly fixed bills have steadily climbed.
Can you reverse lifestyle creep without moving houses?
Yes, you do not need to move houses to reverse lifestyle inflation. You can save $500 to $1,000+ monthly by eliminating auto payment debt, shopping home and auto insurance rates, auditing recurring subscriptions, and cooking three more meals per week at home.
How do you handle lifestyle creep when your social circle spends heavily?
Establish clear personal boundaries by proposing alternative social gatherings that do not require high spending: host dinner parties at home, meet friends for weekend hikes or coffee, and be honest about prioritizing financial independence goals over expensive club dinners.
What is the 50/30/20 budget rule and does it prevent lifestyle inflation?
The 50/30/20 rule allocates 50% of income to Needs, 30% to Wants, and 20% to Savings. While helpful for beginners, high earners should aim for a 50/20/30 or 40/20/40 model, capping fixed needs well below 50% to maximize wealth velocity.
How long does a lifestyle creep reset take to show results?
A comprehensive fixed-cost reset generates dramatic cash flow improvements within 30 to 60 days as newly canceled subscriptions expire, renegotiated insurance premiums take effect, and automated savings sweeps redirect cash away from impulse spending.
Final Thoughts: Simplicity Is the Ultimate Luxury
True financial peace does not come from earning more; it comes from needing less while building more.
When your monthly fixed overhead is low, you possess immense power: you can walk away from toxic bosses, take career sabbaticals, start high-upside ventures, and sleep peacefully through economic downturns without breaking a sweat.
Perform your fixed-cost audit this week, cut the subscriptions that no longer serve you, and build an automated lifestyle baseline that keeps you wealthy for life.
Download: The High-Performance Habit & Energy Operating System
An actionable protocol to eliminate procrastination, protect peak cognitive energy, and engineer frictionless daily focus routines.
- Circadian rhythm & deep sleep architecture
- Frictionless time-blocking calendar blueprint
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Kunal Sharma
Verified AuthorKunal shares actionable advice on time management, daily habits, and career growth. He focuses on helping busy professionals organize their days, stay focused, and achieve their goals without burnout.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search empirical insights, explore our four wisdom categories, and discover curated strategic essays.
Search Insights
Recent Essays
The Backyard Cash Flow Engine: How to House Hack with an ADU in 2026
11 min read • Oct 20How to Become a Fractional COO: Landing Your First $5,000/Month Retainer Client
12 min read • Oct 20The Zero-Bounce Outbound Engine: How to Set Up Multi-Domain Cold Email with Instantly and Clay
12 min read • Oct 20Featured Guides
Further Wisdom & Insights
Explore All Articles
10 Simple Money Habits That Can Make You Wealthier Over Time
Discover 10 simple money habits that help you build wealth over time through smarter saving, budgeting, and intentional spending decisions.
Index Fund Investing for Beginners: The 3-Fund Portfolio (2026)
Master index fund investing with the simple 3-fund portfolio in 2026. Learn exact Vanguard, Fidelity, and Schwab tickers, age allocations, and tax placement.
How to Use ChatGPT & Claude for Personal Finance: 15 Copy-Paste Prompts
Master personal finance using ChatGPT and Claude. Discover 15 ready-to-run prompts for expense audits, zero-based budgeting, and net worth forecasting.