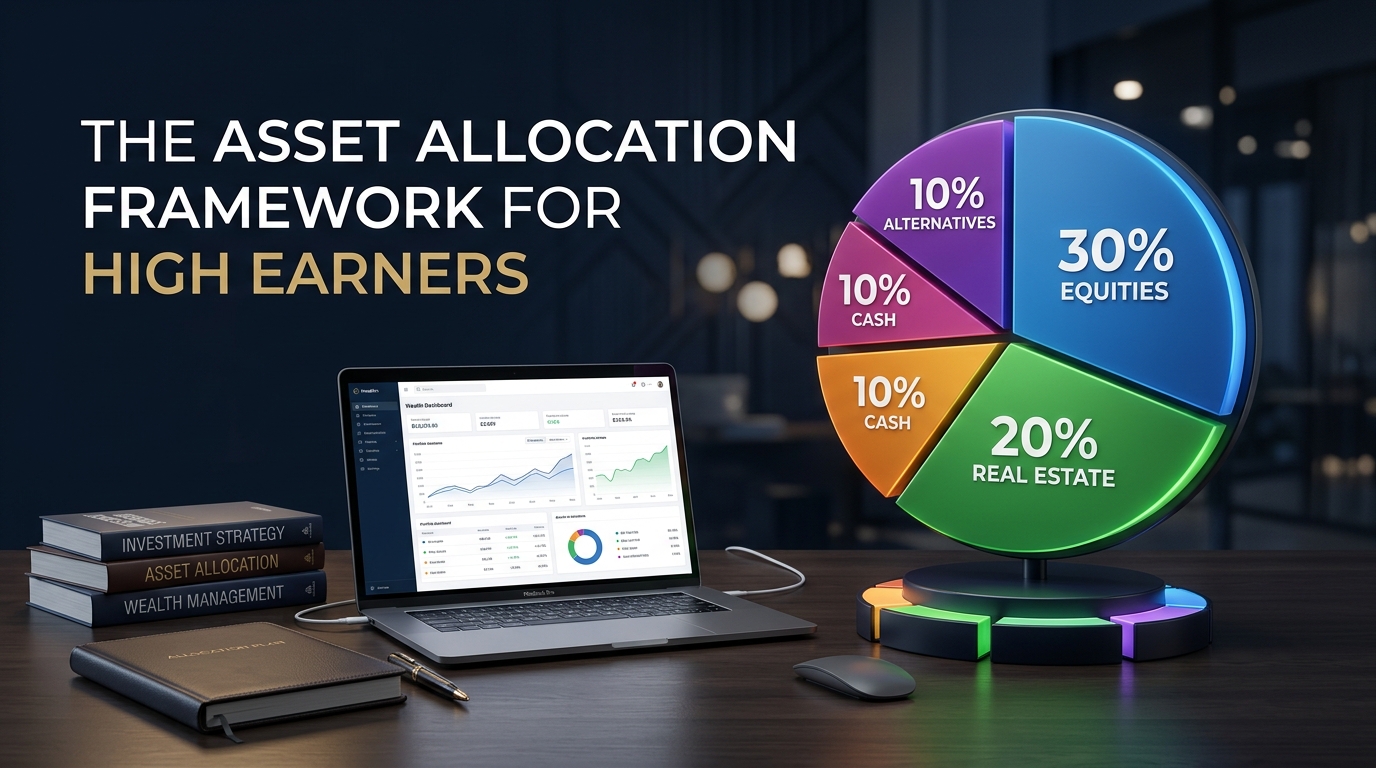
The Asset Allocation Framework for High Earners
How high income turns into enduring wealth through structured capital allocation, risk parity, and illiquid yield reservoirs.
Disclaimer: This article is for educational purposes only and does not constitute financial or legal advice. We may earn an affiliate commission on links at no cost to you.
Read full disclaimer ↓Listen to "The Asset Allocation Framework for High Earners"
Natural Voice Synthesis • Hands-free listening
An asset allocation framework for high earners is a capital distribution strategy that converts active earnings into passive, cash-flowing equity assets. By dividing wealth into three distinct tiers: liquid operating reserves, core compounding equity engines, and asymmetric opportunity funds: high earners protect capital against inflation while building long-term financial independence.
High income is temporary, while asset allocation builds enduring wealth. High earners frequently make the mistake of inflating lifestyle liabilities alongside salary increases. To preserve purchasing power and build financial sovereignty, structure capital across three liquidity tiers: a 0-10% liquid reserve, a 60-75% broad equity core, and a 15-25% asymmetric growth fund.
The income vs. Balance Sheet Paradox
High earned income measures transactional performance, not net worth. Many doctors, corporate executives, and agency owners earning $300,000 to $1,000,000 annually accumulate matching debt liabilities: expensive mortgages, luxury vehicle leases, and high tax bills: leaving their net worth fragile.
True wealth is measured by balance sheet equity that generates yield independent of personal labor. Transitioning from active income to balance sheet equity requires systematic asset allocation rules.
Your earned income measures your transactional efficiency. Your asset allocation measures your structural freedom.
The three-Tier Capital Allocation Engine
High earners should structure personal wealth across three distinct liquidity tiers to balance capital preservation with growth.
                      [ High Active Income Engine ]
                                    |
      +-----------------------------+-----------------------------+
      |                             |                             |
[ Tier 1: Liquid Reserve ]   [ Tier 2: Core Compounding ]   [ Tier 3: Asymmetric Fund ]
 (0-10% Cash/Short Treasuries) (60-75% Index/Real Estate)    (15-25% Private Equity/Bets)
Tier 1: Liquid Operating Reserve (0-10%)
Consists of cash and short-term US Treasury bills dedicated to smoothing cash flow volatility. This capital isn’t designed for aggressive yield; its purpose is to eliminate liquidity risk during market downturns.
Tier 2: Core Compounding Engine (60-75%)
Consists of broad-market index ETFs, global dividend equities, and commercial or residential real estate. This core tier acts as your inflation-hedged wealth engine, compounding tax-efficiently over decades.
Tier 3: Asymmetric Opportunity Fund (15-25%)
Consists of private equity stakes, startup angel investments, business buyouts, or high-margin venture bets. This capital targets non-linear upside where specialized expertise creates alpha.
Practical example: $500,000 Annual Executive Allocation
Consider a corporate executive with $500,000 in net post-tax income after living expenses:
- Tier 1 Allocation ($25,000 / 5%): Directed to High-Yield Treasury Funds to maintain liquid cash reserves.
- Tier 2 Allocation ($350,000 / 70%): $250,000 deployed into Total Stock Market Index ETFs and $100,000 into cash-flowing real estate syndications.
- Tier 3 Allocation ($125,000 / 25%): Deployed into private equity fund commitments and seed-stage software investments.
Over 15 years, Tier 2 forms an unshakeable passive cash flow floor while Tier 3 provides outsized equity upside.
Comparison: Asset Allocation Models for High Earners
| Asset Model | Core Holdings | Downside Protection | Growth Potential | Tax Efficiency |
|---|---|---|---|---|
| Three-Tier Framework | Index Funds, Real Estate, PE | High (Durable reserves) | High (Asymmetric upside) | High |
| Heavy Cash Savings | Cash, High-Yield Savings | Very High (Nominal) | Low (Eroded by inflation) | Moderate |
| Concentrated Crypto / Bets | Altcoins, Speculative Assets | Very Low | Extremely High / Volatile | Low |
| Pure Real Estate Portfolio | Rental Properties, Syndications | Moderate | High (Leveraged yield) | Very High |
Strategic risks and Capital Protection Rules
High earners face unique capital allocation pitfalls that can erode wealth quickly:
- Lifestyle Creep Risk: Increasing personal baseline consumption with every bonus or salary bump prevents capital accumulation.
- Concentration Risk: Holding over 30% of total net worth in company stock or equity options exposes you to catastrophic single-point failure.
- Illiquidity Traps: Over-committing capital to long-term private equity lockups without adequate Tier 1 liquid buffers forces premature asset liquidation during cash crunches.
Frequently asked questions
What ratio of stocks to real estate is optimal for high earners?
A common baseline for high earners is 50-60% broad equity index funds and 20-30% cash-flowing real estate, providing a balance of liquid compounding and tax-advantaged rental income.
How do taxes impact high-earner asset allocation?
High earners face top-bracket income tax rates. Utilizing tax-advantaged accounts (401k, Backdoor Roth IRA, HSAs) and holding index funds for long-term capital gains tax rates significantly improves net compounding returns.
what’s asymmetric upside in capital allocation?
Asymmetric upside occurs when your potential financial return is significantly larger than your total downside risk exposure, such as investing $25,000 in a business with 10x to 50x return potential.
Strategic recommendation
audit your balance sheet today to categorize your current assets into the three liquidity tiers, ensuring your core compounding engine represents at least 60% of total capital.
Download: The Capital Allocation & Wealth Framework PDF
Get our comprehensive 30-page strategic PDF guide covering asset allocation, business moats, and mental models for long-term compounding.
- High-margin enterprise checklist
- Asset allocation proportion matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Written by Eternity Empire Editorial Team
The Eternity Empire editorial team analyzes personal finance, capital allocation, business strategy, and long-term wealth preservation frameworks.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search insights, browse categories, and discover featured publication guides.
Search Insights
Recent Insights
Further Wisdom & Insights
Explore All Articles →
Bitcoin in 2026: Price, Why It's Dropping, and What Comes Next
Bitcoin is near $83,000 after a big drop from its high. Here is why it is falling, what $1,000 would be worth, and if it is too late to buy.
Apple Pay India Launch: How to Set It Up, Where It Works, and What's Missing (2026)
Apple Pay is now live in India with Axis Bank. See how to set it up, which cards work, where to use it, and why UPI is not included yet.
How to Save Money: 12 Simple Ways to Start Saving Today
Learn how to start saving money with easy tips, a fun savings challenge, and the best apps. Find out how much to save each month and what to keep in a savings account.