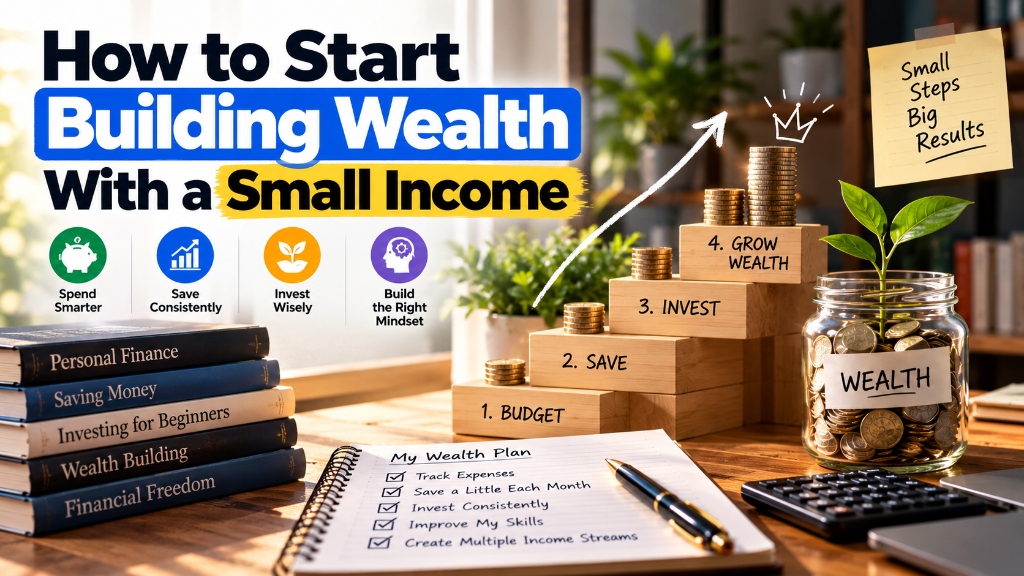
How to Start Building Wealth With a Small Income
Practical strategies to save your first $10,000, advantage high-yield automated investing, and break the paycheck-to-paycheck cycle.
Disclaimer: This article is for educational purposes only and does not constitute financial or legal advice. We may earn an affiliate commission on links at no cost to you.
Read full disclaimer ↓Listen to "How to Start Building Wealth With a Small Income"
Natural Voice Synthesis • Hands-free listening
Building wealth with a modest income requires prioritizing capital retention, eliminating high-interest liabilities, and leveraging compound interest through automated dollar-cost averaging. Wealth accumulation is fundamentally driven by your savings rate and time in the market rather than starting income size.
You don’t need a massive salary to start building wealth. By securing a $1,000 liquid emergency reserve, eliminating toxic credit card debt, and automatically allocating even $50 to $150 monthly into broad-market index funds, small incomes compound into significant net worth over time. Focus on consistency over initial capital size.
The myth of High Income Wealth
A widespread misconception causes millions to delay investing: the belief that capital growth requires thousands of dollars in spare monthly cash. In reality, wealth building is a behavioral system established early.
Developing financial discipline on a $40,000 income builds the structural capability to manage $200,000 effectively later. Conversely, high earners who lack capital retention habits frequently live paycheck-to-paycheck despite large salaries.
Step-by-Step Blueprint for Small-Income Wealth Creation
Follow this three-step blueprint to transition from financial fragility to compounding asset growth.
Step 1: Secure a $1,000 Starter Reserve
Before initiating aggressive market investments, build a $1,000 liquid starter cushion in a high-yield savings account. This reserve prevents minor surprises (such as vehicle repairs or medical co-pays) from forcing you onto high-interest credit cards.
Step 2: Eliminate Toxic High-Interest Debt
Any debt with an interest rate exceeding 10% (such as credit cards or payday loans) acts as a negative financial engine. Paying off an 18% APR credit card balance yields a guaranteed, tax-free 18% return on capital, which outperforms average stock market returns.
Step 3: Automate Micro-Investing in Index Funds
Utilize broad-market index fund ETFs (such as total stock market or S&P 500 index funds) that allow fractional share purchases starting at $10. Set up automated monthly deposits to use dollar-cost averaging.
Monthly Contribution: $150 / month
Assumed Annual Growth: 8% Average Market Return
Principal Invested (25 Years): $45,000
Projected Portfolio Value (25 Years): ~$142,000
Consistency of small contributions over long time horizons always outperforms sporadic large investments.
Practical example: Compounding Micro-Contributions
Consider an investor saving $100 per month starting at age 22 versus waiting until age 35 to invest $250 per month:
- Early Micro-Investor (Age 22 to 65): Invests $100 monthly ($51,600 total principal). At an 8% average return, the portfolio grows to approximately $462,000 by age 65.
- Delayed Investor (Age 35 to 65): Invests $250 monthly ($90,000 total principal). At the same 8% return, the portfolio reaches approximately $373,000 by age 65.
Starting early with small amounts yields $89,000 more wealth despite contributing $38,400 less total cash out of pocket.
Comparison: Early Wealth Strategies
| Strategy | Ideal Capital Size | Risk Profile | Long-Term Return | Ease of Execution |
|---|---|---|---|---|
| Broad Index ETFs | Any amount ($10+) | Moderate | High (8-10% historical) | Very Easy (Automated) |
| High-Yield Savings | Any amount | Very Low | Low (3-5%) | Extremely Easy |
| Individual Stock Picking | Requires research capital | High | Volatile / Uncertain | Hard (Requires skill) |
| High-Interest Debt Payoff | Debt balance sum | Zero | Guaranteed 15-25% return | Moderate |
Common pitfalls and Strategic Mistakes
Avoid these financial traps when building wealth on a modest income:
- Chasing Speculative Investments: Gambling on volatile meme coins or micro-cap stocks in search of quick riches usually leads to total capital loss.
- Lifestyle Creep: Elevating your monthly expenses every time you receive a minor pay raise neutralizes wealth accumulation.
- Waiting for the Perfect Time: Postponing investment until you earn a higher income forfeits your most valuable asset: compounding time.
Frequently asked questions
Can I really build wealth investing only $50 a month?
Yes. Investing $50 monthly at an 8% return yields over $74,000 across 30 years from just $18,000 in total out-of-pocket contributions. More importantly, it establishes permanent investing habits.
Should I pay off my student loans before investing in index funds?
If your student loans carry low fixed interest rates (under 4-5%), you can invest in index funds while making standard monthly debt payments. If student loans carry high variable rates (8%+), prioritize aggressive debt payoff.
what’s dollar-cost averaging?
Dollar-cost averaging is the practice of investing a fixed dollar amount into the market at regular intervals, regardless of share price fluctuations, reducing market timing risk.
Strategic recommendation
open a low-cost brokerage account today, enable fractional share trading, and set up an automated $50 monthly transfer into a broad-market index ETF.
Download: The Capital Allocation & Wealth Framework PDF
Get our comprehensive 30-page strategic PDF guide covering asset allocation, business moats, and mental models for long-term compounding.
- High-margin enterprise checklist
- Asset allocation proportion matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Written by Eternity Empire Editorial Team
The Eternity Empire editorial team analyzes personal finance, capital allocation, business strategy, and long-term wealth preservation frameworks.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search insights, browse categories, and discover featured publication guides.
Search Insights
Recent Insights
Further Wisdom & Insights
Explore All Articles →
Bitcoin in 2026: Price, Why It's Dropping, and What Comes Next
Bitcoin is near $83,000 after a big drop from its high. Here is why it is falling, what $1,000 would be worth, and if it is too late to buy.
Apple Pay India Launch: How to Set It Up, Where It Works, and What's Missing (2026)
Apple Pay is now live in India with Axis Bank. See how to set it up, which cards work, where to use it, and why UPI is not included yet.
How to Save Money: 12 Simple Ways to Start Saving Today
Learn how to start saving money with easy tips, a fun savings challenge, and the best apps. Find out how much to save each month and what to keep in a savings account.