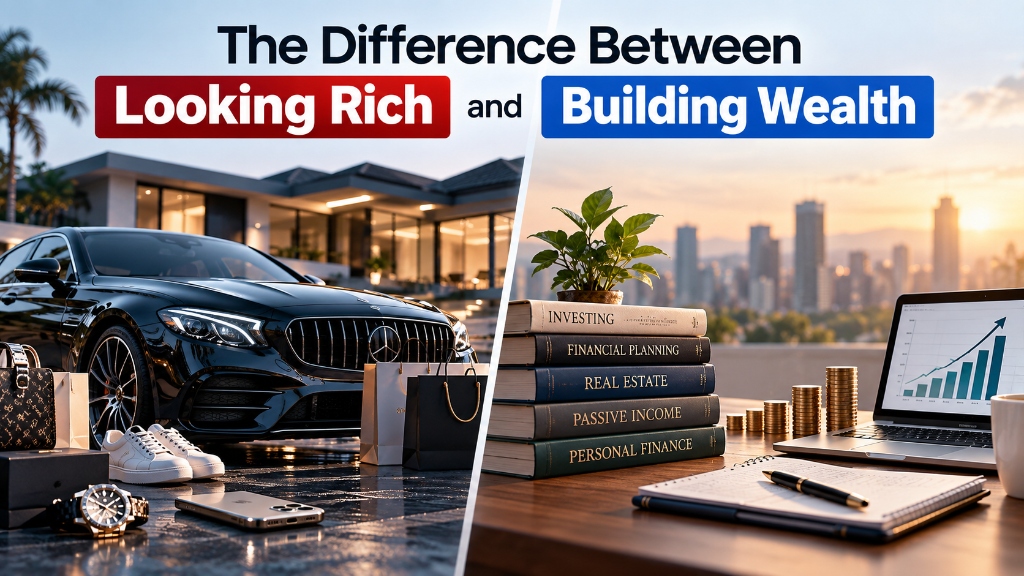
The Difference Between Looking Rich and Building Wealth
Why high income isn't wealth, how status traps drain your future, and how to build quiet, enduring financial independence.
Disclaimer: This article is for educational purposes only and does not constitute financial or legal advice. We may earn an affiliate commission on links at no cost to you.
Read full disclaimer ↓Listen to "The Difference Between Looking Rich and Building Wealth"
Natural Voice Synthesis • Hands-free listening
The difference between looking rich and building wealth lies in the contrast between current consumption display and accumulated asset equity. Looking rich means spending active income on depreciating luxury goods to signal status, whereas building wealth means quietly accumulating cash-flowing assets that compound financial autonomy.
Display wealth is visible consumption: expensive vehicles, high-end apparel, and luxury housing funded by debt or high burn rates. True wealth is invisible equity: index fund portfolios, business ownership, real estate holdings, and calendar sovereignty. Prioritize asset retention over social status display to build permanent independence.
The illusion of Display Wealth
Modern digital culture confuses income spending with wealth accumulation. When an individual drives a $100,000 luxury vehicle down the street, the only empirical data point you possess is that they have $100,000 less cash than before buying it, or they have taken on a monthly liability that restricts future flexibility.
In The Psychology of Money, Morgan Housel captured this fundamental dynamic:
Wealth is what you don’t see. Wealth is the nice cars not purchased. It’s the watches not worn, the clothes passed up and the first-class upgrade declined. Wealth is financial assets that haven’t yet been converted into the stuff you see.
High Income + High Consumption = Zero Leverage (Looking Rich)
High Income + Capital Discipline = Enduring Wealth (Financial Sovereignty)
Money as Consumption vs. Money as Capital
Building real wealth requires shifting your mental model of currency from consumption tokens to economic capital.
- Consumption Dollars: Money spent on items that depreciate immediately or carry recurring maintenance drag (luxury vehicles, designer clothing, high-end dining).
- Capital Dollars: Money deployed into assets that yield positive return on investment or appreciate faster than inflation (index funds, income-producing real estate, equity shares).
Three core principles of Quiet Wealth Accumulation
Adopt these core principles to break free from the status trap and build balance sheet strength.
1. Decouple Consumption From Income Growth
As your professional earning capacity expands, maintain a fixed baseline expense structure. Direct 80%+ of incremental raises and bonuses straight into wealth-generating assets.
2. Value Time Sovereignty Over External Status
The highest dividend money pays is control over your time. Being able to wake up every morning and decide how to spend your day provides far greater long-term satisfaction than social display approval.
3. Build Automated Reinvestment Engines
Set up automated systems where investment dividends and interest reinvest automatically without requiring manual willpower decisions.
Practical example: The Tale of Two Earners
Consider two professionals earning $200,000 net annually over 15 years:
- Earner A (Status Focused): Leases luxury vehicles ($1,400/mo), lives in an expensive apartment ($4,500/mo), and spends $2,000 monthly on high-end dining and designer goods. Total net worth after 15 years: $85,000 (mostly depreciating vehicle equity).
- Earner B (Wealth Focused): Drives a reliable used vehicle ($0 loan), maintains modest housing ($2,200/mo), and automatically invests $5,000 monthly into index funds and real estate. Total net worth after 15 years: $1,750,000 generating $70,000 in passive annual yield.
Comparison: Looking Rich vs. Building Wealth
| Dimension | Looking Rich | Building Wealth |
|---|---|---|
| Primary Metric | Monthly spending & display | Net worth & passive yield |
| Vehicle Choice | Leased high-end luxury | Owned reliable vehicle |
| Primary Asset Type | Depreciating consumer goods | Index funds, real estate, equity |
| Financial Stress | High (Vulnerable to income loss) | Low (Protected by reserves) |
| Calendar Control | Low (Bound to high active income) | High (Freedom to choose work) |
Common status traps to Avoid
Beware of these common financial traps that erode net worth:
- The Lifestyle Inflation Spiral: Immediately raising living standards following every salary increase.
- Financing Depreciating Assets: Taking out long-term high-interest loans for items that drop in value.
- Spending for Digital Validation: Purchasing experiences or items primarily to post photos on social networks.
Frequently asked questions
Is it wrong to enjoy luxury goods if I earn a high income?
No, enjoying luxury goods is fine provided your capital allocation engine is fully funded first. The danger arises when luxury consumption displaces passive asset accumulation.
How can I resist peer pressure to spend money on status display?
Shift your primary metric of success from external display to net worth accumulation and calendar autonomy. Measure success by your freedom, not your monthly expenditure.
what’s the first step to transition from looking rich to building wealth?
Audit your current monthly subscription and discretionary spending, identify depreciating liabilities, and direct that cash flow into automated index fund purchases.
Strategic recommendation
review your last 90 days of personal expenditures today. Identify one major display expense and reallocate that cash flow toward automated index fund investments.
Download: The Capital Allocation & Wealth Framework PDF
Get our comprehensive 30-page strategic PDF guide covering asset allocation, business moats, and mental models for long-term compounding.
- High-margin enterprise checklist
- Asset allocation proportion matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Written by Eternity Empire Editorial Team
The Eternity Empire editorial team analyzes personal finance, capital allocation, business strategy, and long-term wealth preservation frameworks.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search insights, browse categories, and discover featured publication guides.
Search Insights
Recent Insights
Further Wisdom & Insights
Explore All Articles →
Bitcoin in 2026: Price, Why It's Dropping, and What Comes Next
Bitcoin is near $83,000 after a big drop from its high. Here is why it is falling, what $1,000 would be worth, and if it is too late to buy.
Apple Pay India Launch: How to Set It Up, Where It Works, and What's Missing (2026)
Apple Pay is now live in India with Axis Bank. See how to set it up, which cards work, where to use it, and why UPI is not included yet.
How to Save Money: 12 Simple Ways to Start Saving Today
Learn how to start saving money with easy tips, a fun savings challenge, and the best apps. Find out how much to save each month and what to keep in a savings account.