The Rules of Asymmetric Investing for Private Wealth
How sophisticated investors structure portfolios where downside risk is strictly capped while potential financial returns remain uncapped.
Disclaimer: This article is for educational purposes only and does not constitute financial or legal advice. We may earn an affiliate commission on links at no cost to you.
Read full disclaimer ↓Listen to "The Rules of Asymmetric Investing for Private Wealth"
Natural Voice Synthesis • Hands-free listening
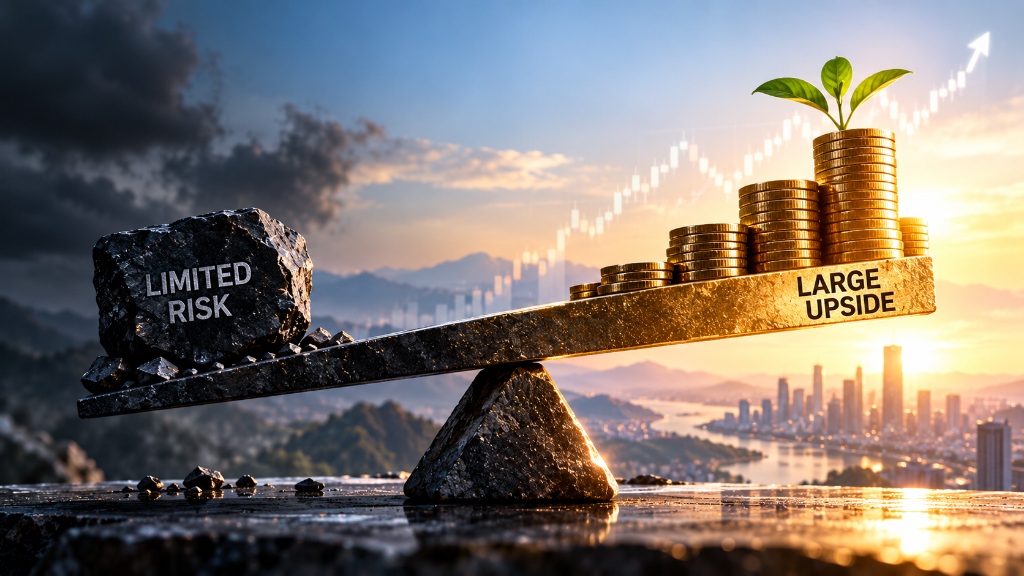
Asymmetric investing is the strategy of identifying opportunities where potential financial gains far exceed quantifiable downside losses. Rather than taking symmetrical 50-50 bets, disciplined wealth builders structure positions so a total loss costs 1x while success generates 5x, 10x, or 100x returns.
Asymmetric investing pairs strictly defined downside protection with open-ended upside potential. Investors achieve asymmetry by allocating small capital tranches to high-convexity assets, negotiating floor protections, and utilizing options or venture-style payoff structures. The golden rule is simple: never risk more than 1% to 2% of total portfolio net worth on a single asymmetric bet.
what’s asymmetric risk-Reward?
Asymmetric risk-reward exists when the mathematical expected value of an asset skew heavily toward positive returns. In conventional public equity markets, standard index investing offers symmetric returns where upside and downside scale in roughly equal proportion to market volatility. Asymmetric bets break this symmetry by limiting loss exposure through structural contractual floors or capped capital sizing.
The barbell allocation system
popularized by risk analysts, the Barbell Strategy splits portfolio capital into two extreme exposure categories while avoiding fragile middle-risk assets.
Safety core (85% to 90% of Portfolio)
The vast majority of wealth sits in ultra-safe capital preservation instruments: short-duration Treasuries, inflation-indexed securities, and cash reserves. This core ensures that no market collapse or black swan event can threaten personal financial solvency.
Convexity engine (10% to 15% of Portfolio)
The remaining minor allocation goes into asymmetrical bets: seed-stage private equity, mispriced digital assets, out-of-the-money long-duration options, or early-stage technology ventures. Because this capital is small, losing 100% of it causes minimal harm, whereas a 20x gain on the tranche expands total portfolio wealth significantly.
Strategic comparison: Investment Risk Profiles
| Strategy | Downside Risk | Upside Potential | Mathematical Convexity | Primary Goal |
|---|---|---|---|---|
| Symmetrical Indexing | High (-40% in crash) | Moderate (+8% annual) | Low (1:1 Ratio) | Steady Capital Accumulation |
| Concentrated Single Stock | Extreme (-100%) | High (+3x to +5x) | Poor (Uncapped Loss) | Speculative Growth |
| Fixed Income Bonds | Moderate (Inflation Drag) | Low (Fixed Coupon) | Negative in Inflation | Income Generation |
| Barbell Asymmetric System | Capped (Max 15% Tranche) | Uncapped (+10x to +50x) | High (1:5+ Ratio) | Wealth Explosion with Protection |
How to Evaluate Asymmetric Opportunities in 4 Steps
Finding true asymmetric bets requires evaluating downside risk before even contemplating potential profits.
- Calculate the Maximum Ruin Cost: Determine the exact dollars lost if the investment goes to absolute zero. If loss exceeds 2% of liquid net worth, pass or resize down.
- Identify Structural Floor Protections: Look for hard assets, liquidation preferences, patents, or secondary market resale values that cap potential losses.
- Verify Uncapped Growth Drivers: Confirm that revenues scale exponentially through digital distribution, network effects, or massive total addressable market expansions.
- Demand a Minimum 5:1 Expected Ratio: Only deploy speculative capital if plausible upside scenarios deliver at least five dollars of profit for every dollar at risk.
Real world case example: Venture Capital vs Real Estate
Consider an investor evaluating two private opportunities with $50,000 in discretionary capital:
Opportunity A involves putting $50,000 as a 20% down payment on a leveraged rental property. If local real estate drops 25%, the investor faces mortgage default and personal credit liability far exceeding the initial $50,000. Downside is amplified by advantage.
Opportunity B splits $50,000 into five $10,000 checks across five early-stage software startups. Four of the five startups fail completely, wiping out $40,000. However, the fifth startup hits product-market fit and returns 30x ($300,000). The net outcome yields $300,000 on a $50,000 total outlay despite an 80% project failure rate.
Frequently asked questions
Can retail investors implement asymmetric investing without angel access?
Yes, retail investors achieve asymmetry using long-dated options strategies like LEAPs, buying mispriced small-cap equities with fortress balance sheets, or participating in asymmetric industry tailwinds. Sizing the position small is what creates the asymmetrical safety profile.
what’s the biggest error people make with asymmetric bets?
The single largest error is position sizing. Investors find a great asymmetric idea and allocate 40% of their liquid net worth into it. When an unexpected shock occurs, the total loss devastates their financial foundation, turning an asymmetric opportunity into catastrophic ruin.
How does inflation affect asymmetric portfolio planning?
Inflation erodes the safety side of the barbell if cash yields zero. To counter this, keep safety capital in short-duration Treasury inflation-protected securities (TIPS) or high-yield money market accounts that adjust yields alongside benchmark interest rate shifts.
Download: The Capital Allocation & Wealth Framework PDF
Get our comprehensive 30-page strategic PDF guide covering asset allocation, business moats, and mental models for long-term compounding.
- High-margin enterprise checklist
- Asset allocation proportion matrix
This article and its associated calculators are for educational and informational purposes only and do not constitute financial, investment, legal, tax, or medical advice. We may earn an affiliate commission on third-party links at zero cost to you. Always consult a licensed professional before making major financial, health, or investment decisions. Read our full Legal & Financial Disclaimer.
Written by Eternity Empire Editorial Team
The Eternity Empire editorial team analyzes personal finance, capital allocation, business strategy, and long-term wealth preservation frameworks.
Was this essay valuable to you?
Help us refine our editorial focus and research priorities.
Reader Discussion (2)
Extremely well-articulated analysis on capital compounding. The breakdown on equity allocation vs active income is spot on.
The distinction between looking rich and building real moats is something more founders need to study deeply.
Explore Eternity Empire
Search insights, browse categories, and discover featured publication guides.
Search Insights
Recent Insights
Further Wisdom & Insights
Explore All Articles →
Bitcoin in 2026: Price, Why It's Dropping, and What Comes Next
Bitcoin is near $83,000 after a big drop from its high. Here is why it is falling, what $1,000 would be worth, and if it is too late to buy.
Apple Pay India Launch: How to Set It Up, Where It Works, and What's Missing (2026)
Apple Pay is now live in India with Axis Bank. See how to set it up, which cards work, where to use it, and why UPI is not included yet.
How to Save Money: 12 Simple Ways to Start Saving Today
Learn how to start saving money with easy tips, a fun savings challenge, and the best apps. Find out how much to save each month and what to keep in a savings account.